INSIGHTMarkets and EconomicsInsight
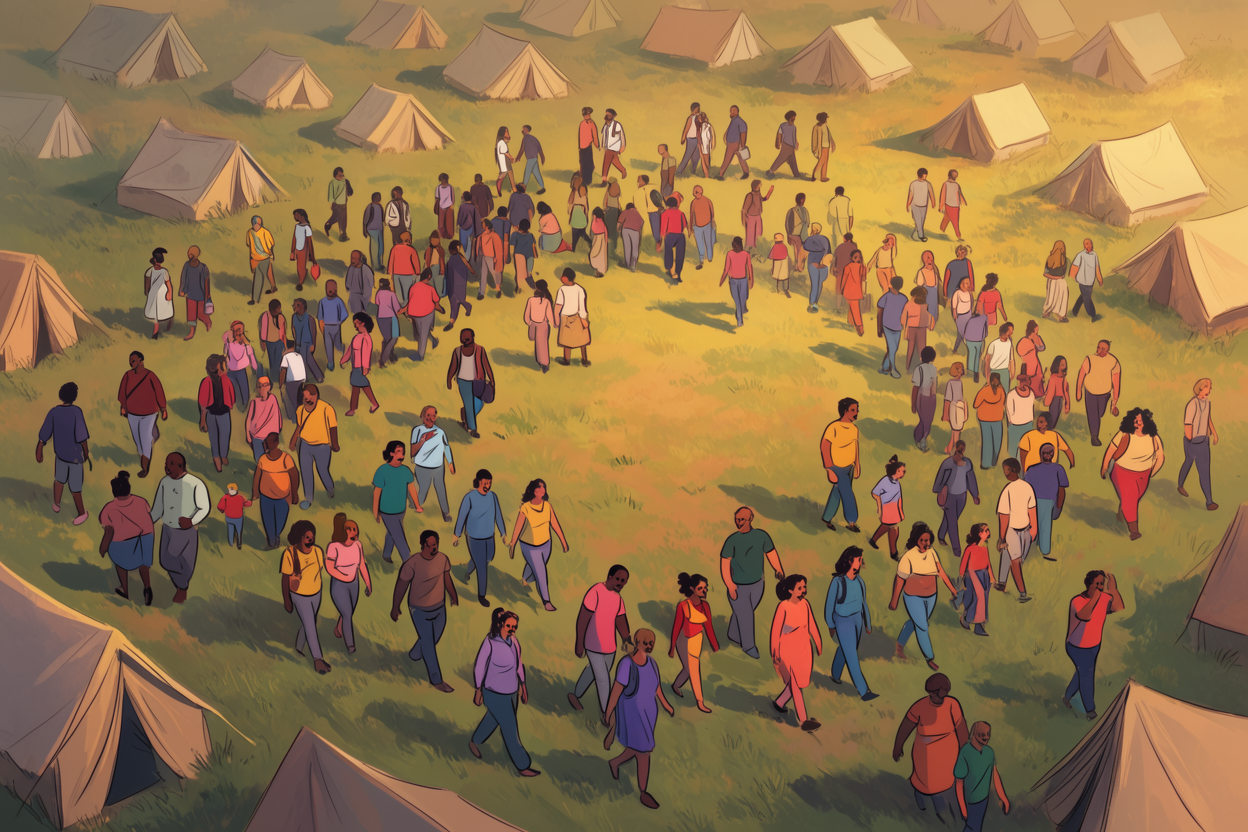
The Investment Implications of Deglobalisation
How supply-chain localisation is reshaping manufacturing and capital expenditure
ET&A Research · 28 July 2026 · 12 min read
MCK · NYSE · Healthcare / Distribution
McKesson Corporation provides healthcare services in the United States and internationally.
Current price
$974.89
▲ +$13.01 (1.35%) today
ET&A View
Last reviewed 22 September 2026
ET&A sees limited reason to buy aggressively or sell at the current price.
McKesson is a reasonable business with some weak spots.
Business Health
Is the business financially healthy?
Mostly healthy
Revenue, earnings and the balance sheet stand out. Watch margins.
Overall
Revenue
$403.4bn · ↑ +12% last year
Earnings
$4.6bn · ↑ +45% last year
Margins
Keeps 2% of sales as operating profit
Cash generation
$5.4bn spare cash a year · 1% of sales
Balance sheet
Debt ≈ 0.6 years of earnings
Dividend
0.4% yield · Pays out 9% of earnings · covered 11.4×
Investor View
Open a section for the detail behind the quick view.
The ET&A Score for McKesson Corporation is 5.7/10 — blending a Quant Score of 5.0/10, fundamental conviction of 5.7/10 and valuation attractiveness of 7.9/10. Business quality is assessed as average (EBITDA margin 2%,…
The complete ET&A view
See our full reasoning, what could drive the shares higher or go wrong, our Fair Value and Preferred Entry, and how our view has changed.
Reported annual results, newest first · Market data. “Growth” is the change in sales on the year before.
| Year | Revenue | Growth | Operating margin | Net income | EPS | Free cash flow |
|---|---|---|---|---|---|---|
| FY2026 | $403.4bn | +12.4% | 1.6% | $4.8bn | $38.38 | $5.4bn |
| FY2025 | $359.1bn | +16.2% | 1.3% | $3.3bn | $25.72 | $5.2bn |
| FY2024 | $309.0bn | +11.7% | 1.4% | $3.0bn | $22.39 | $3.6bn |
| FY2023 | $276.7bn | — | 1.7% | $3.6bn | $25.03 | $4.6bn |
Long-term growth investors
Also suits: Adventurous investors comfortable with big swings
We don’t cover another company in this sector yet.
Compare McKesson with any company → The model’s own peer calculations are in the Research View.
McKesson Corporation (MCK) is listed on NYSE, United States, in Healthcare. Market capitalisation is approximately $100.3bn. McKesson Corporation provides healthcare services in the United States and internationally. It operates through four segments: North American Pharmaceutical, Oncology & Multispecialty, Prescription Technology Solutions, and Medical-Surgical Solutions.
Healthcare / Distribution · United States
For detailed analysis. Each section opens on its own.
As of 14 October 2026
Standard ways of comparing the share price with the company’s earnings, sales and cash. Tap the “i” for what each one means.
| Measure | Today | Source |
|---|---|---|
| P/E | Members | |
| Forward P/E | Members | |
| EV/EBITDA | Members | |
| Price/Sales | Members | |
| FCF Yield | Members |
Valuation ratios are part of ET&A membership.
Use the 5Y and Max ranges on the price chart at the top of the page.
Forecasts are market consensus or calculated from forward EPS — not ET&A estimates, and they can be wrong.
Powered by the ET&A Valuation FrameworkHow Fair Value & Preferred Entry work →
Read the full ET&A methodology →The ET&A View combines our assessment of the business with where today’s price sits against our Preferred Entry and Fair Value. It is a considered judgement, not a mechanical score.
ET&A Score: ET&A's overall assessment of business quality, valuation, growth and risk, out of 10. It weighs business quality, financial strength, growth, valuation, risk, future prospects.
Powered by the ET&A Company Assessment FrameworkSee the full framework →
The automatic, rules-based scores that feed our research. The ET&A Score blends these with our own analysis of the business and its value. How the framework works →
Unprofitable · Sound · Strong
Context — not part of the score
Valuation and share-price swings describe the shares, not the company, so they are judged in the ET&A Score and View instead.
Based on the factors that could be measured (45% of the model).
Each area is scored from 0 to 10 on ET&A’s methodology scales — the same ones our research uses — then given a word: Excellent from 8.5, Strong from 7, Good from 5.5, Average from 4.5, Below Average from 3, Weak below 3. The overall answer is the average of the areas we could rate (at least three); the dividend isn’t part of it.
| Area | Based on | Score | Rating |
|---|---|---|---|
| Revenue |
Rated on 3-year average revenue growth, on ET&A's growth scale. | 7.7 / 10 | Strong |
| Earnings |
Rated on 3-year average earnings growth, on ET&A's growth scale. | 7.0 / 10 | Strong |
| Margins |
The average of operating and net margin, each scored on ET&A's margin scales. A negative margin scores 1 (Weak). | 3.3 / 10 | Below Average |
| Cash generation |
Free cash flow as a share of sales, on ET&A's cash-generation scale. | 4.5 / 10 | Average |
| Balance sheet |
Net debt ÷ EBITDA — roughly how many years of operating earnings would repay the debt — on ET&A's leverage scale. | 7.9 / 10 | Strong |
| Dividend |
Dividend yield on ET&A's income scale. Not part of the overall health rating. | 1.8 / 10 | Weak |
| Overall | Average of the 5 rated areas | 6.1 / 10 | Good |
Where each band starts on the scales above. They are fixed and identical for every company we cover; they come straight from ET&A’s methodology, so a company is judged the same way here as in our research.
| Measure | Excellent | Strong | Good | Average | Below Average | Weak |
|---|---|---|---|---|---|---|
| GrowthStructural Growth (Fundamental Conviction) | 18%+ | 10%+ | 5.0%+ | 1.7%+ | −2.5%+ | below −2.5% |
| Operating marginCompetitive Position (Fundamental Conviction) | 29%+ | 20%+ | 13%+ | 7.5%+ | 0%+ | below 0% (loss) |
| Net marginEarnings Durability (Fundamental Conviction) | 23%+ | 15%+ | 9.8%+ | 6.0%+ | 0%+ | below 0% (loss) |
| Free-cash-flow marginCapital Allocation (Fundamental Conviction) | 15%+ | 8.5%+ | 3.8%+ | 1.3%+ | −2.5%+ | below −2.5% |
| Net debt ÷ EBITDAStructural Risk (Fundamental Conviction) | net cash | ≤ 1.5× | ≤ 2.8× | ≤ 3.6× | ≤ 5.0× | above 5.0× |
| Return on equity (banks & insurers)Bank and insurer quality | 16%+ | 12%+ | 9.0%+ | 6.7%+ | 2.7%+ | below 2.7% |
| Equity ÷ assetsBank capital | 7.5%+ | 6.0%+ | 4.7%+ | 4.0%+ | any | — |
| Dividend yieldIncome factor (ET&A Quant Score) | 5.8%+ | 4.0%+ | 2.5%+ | 1.8%+ | 1.0%+ | below 1.0% |
Band floors: Excellent 8.5 · Strong 7 · Good 5.5 · Average 4.5 · Below Average 3 (scores out of 10). Utilities and property companies’ structural debt is scored 6.5, as in ET&A’s risk model.
No research notes have been published for McKesson yet.
Need deeper analysis on McKesson? ET&A Professional includes full company notes, valuations and models — or commission bespoke research.
How supply-chain localisation is reshaping manufacturing and capital expenditure
ET&A Research · 28 July 2026 · 12 min read
Payments built Africa’s fintech industry by solving one of the continent’s most visible financial problems. The next generation of winners, however, will need to use that foundation to provide credit, savings, insurance and the broader financial infrastructure that households and businesses still lack.
ET&A Research · 28 July 2026 · 9 min read
Once viewed as specialist technology facilities, data centres are increasingly becoming essential infrastructure. Rising demand for cloud computing and AI is turning them into a long-term asset class for investors.
ET&A Research · 24 July 2026 · 6 min read